What Happens When Central Banks Stop Buying Bonds and Begin Shrinking Their Balance Sheets
“If Quantitative Easing is like adding water to keep an economic engine running during difficult times, Quantitative Tightening is the careful process of draining that extra liquidity once conditions begin to normalize. The challenge is not simply removing support—but doing so without unsettling the financial system.”
Introduction: Every Extraordinary Policy Must Eventually End
Imagine a patient recovering in a hospital.
During a serious illness, doctors provide intensive treatment to stabilize the patient’s condition. As recovery begins, those emergency measures are gradually reduced.
Continuing extraordinary treatment indefinitely may create new complications.
The same principle applies to monetary policy.
During severe economic disruptions, central banks may purchase large quantities of government bonds through Quantitative Easing (QE) to support financial markets and economic activity.
But what happens when inflation rises, economic conditions improve, or policymakers conclude that emergency support is no longer appropriate?
The answer often involves Quantitative Tightening (QT).
QT represents the gradual withdrawal of extraordinary monetary accommodation.
Understanding this process is essential because it can influence bond prices, interest rates, financial market liquidity, and investment decisions around the world.
What Is Quantitative Tightening?
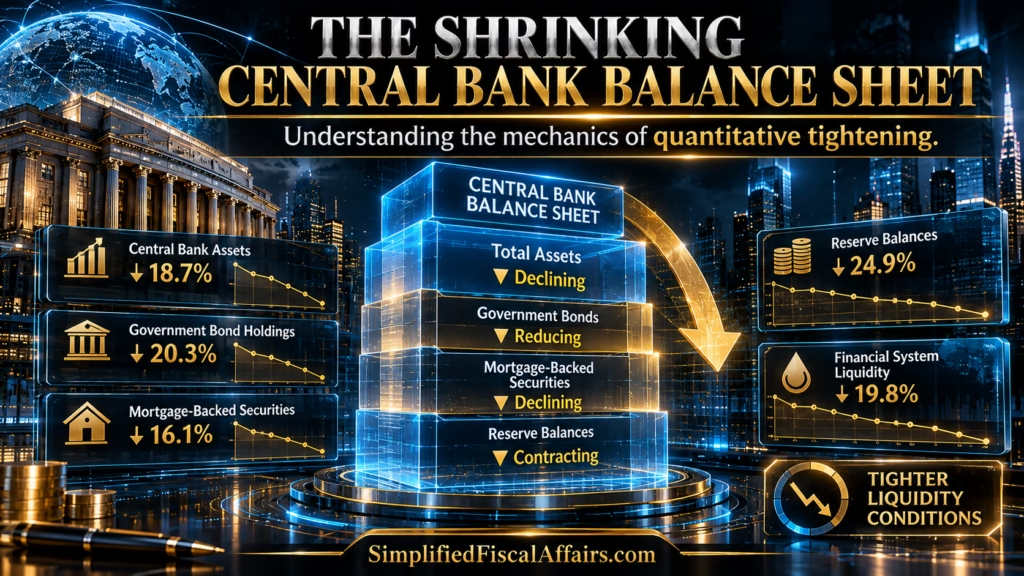
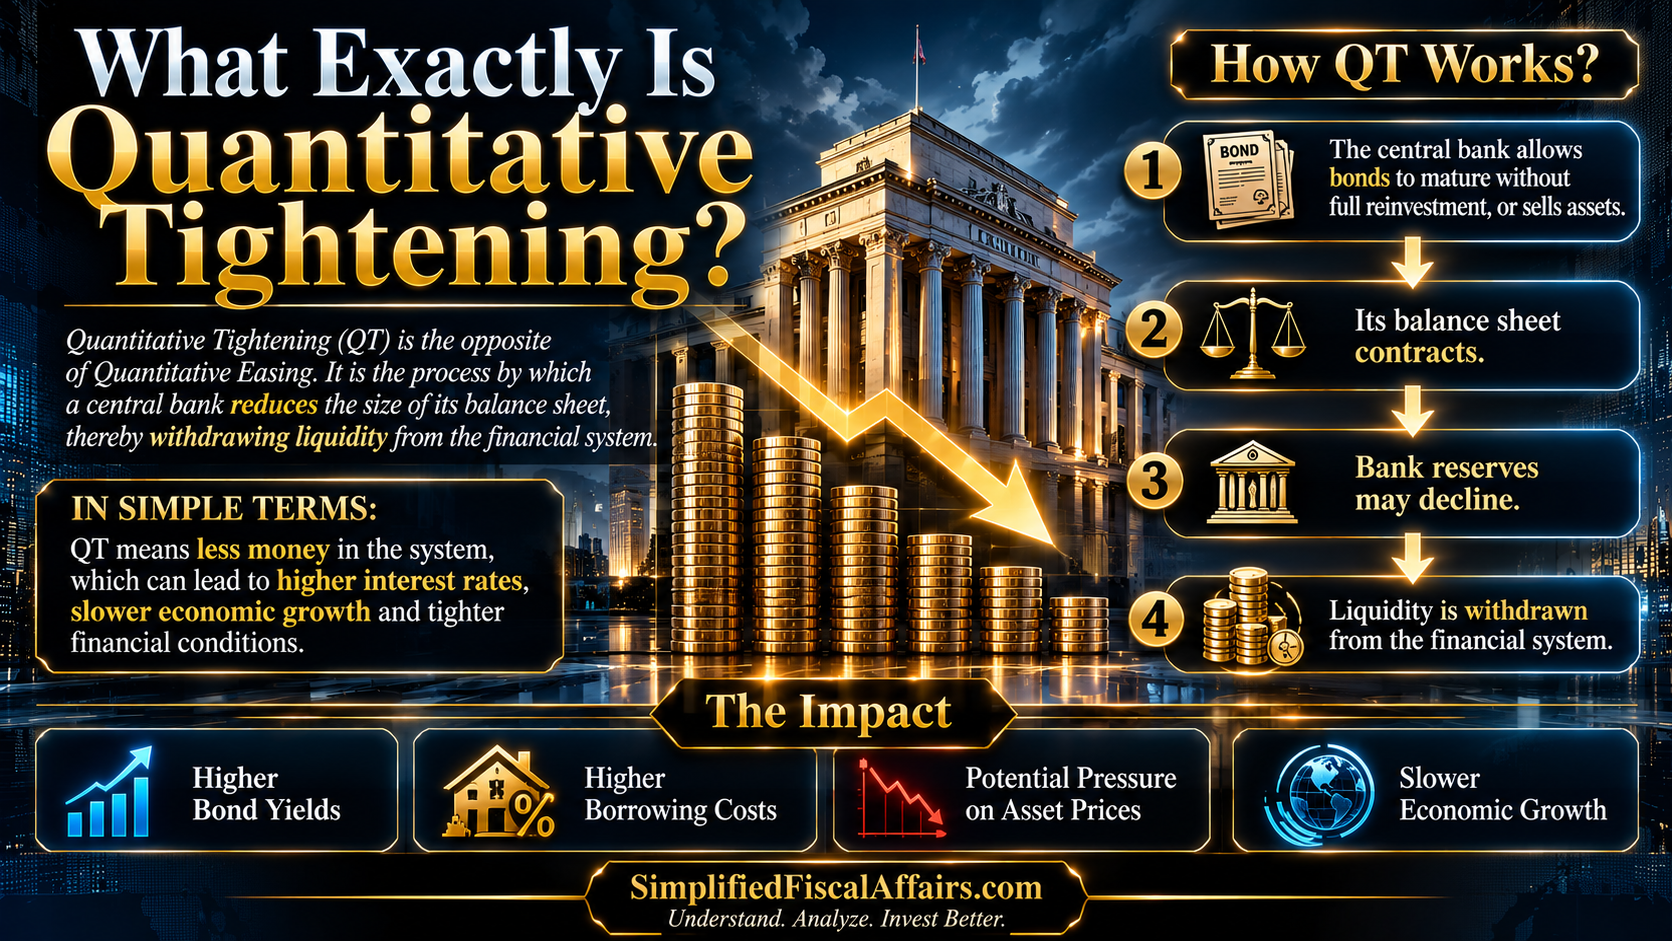
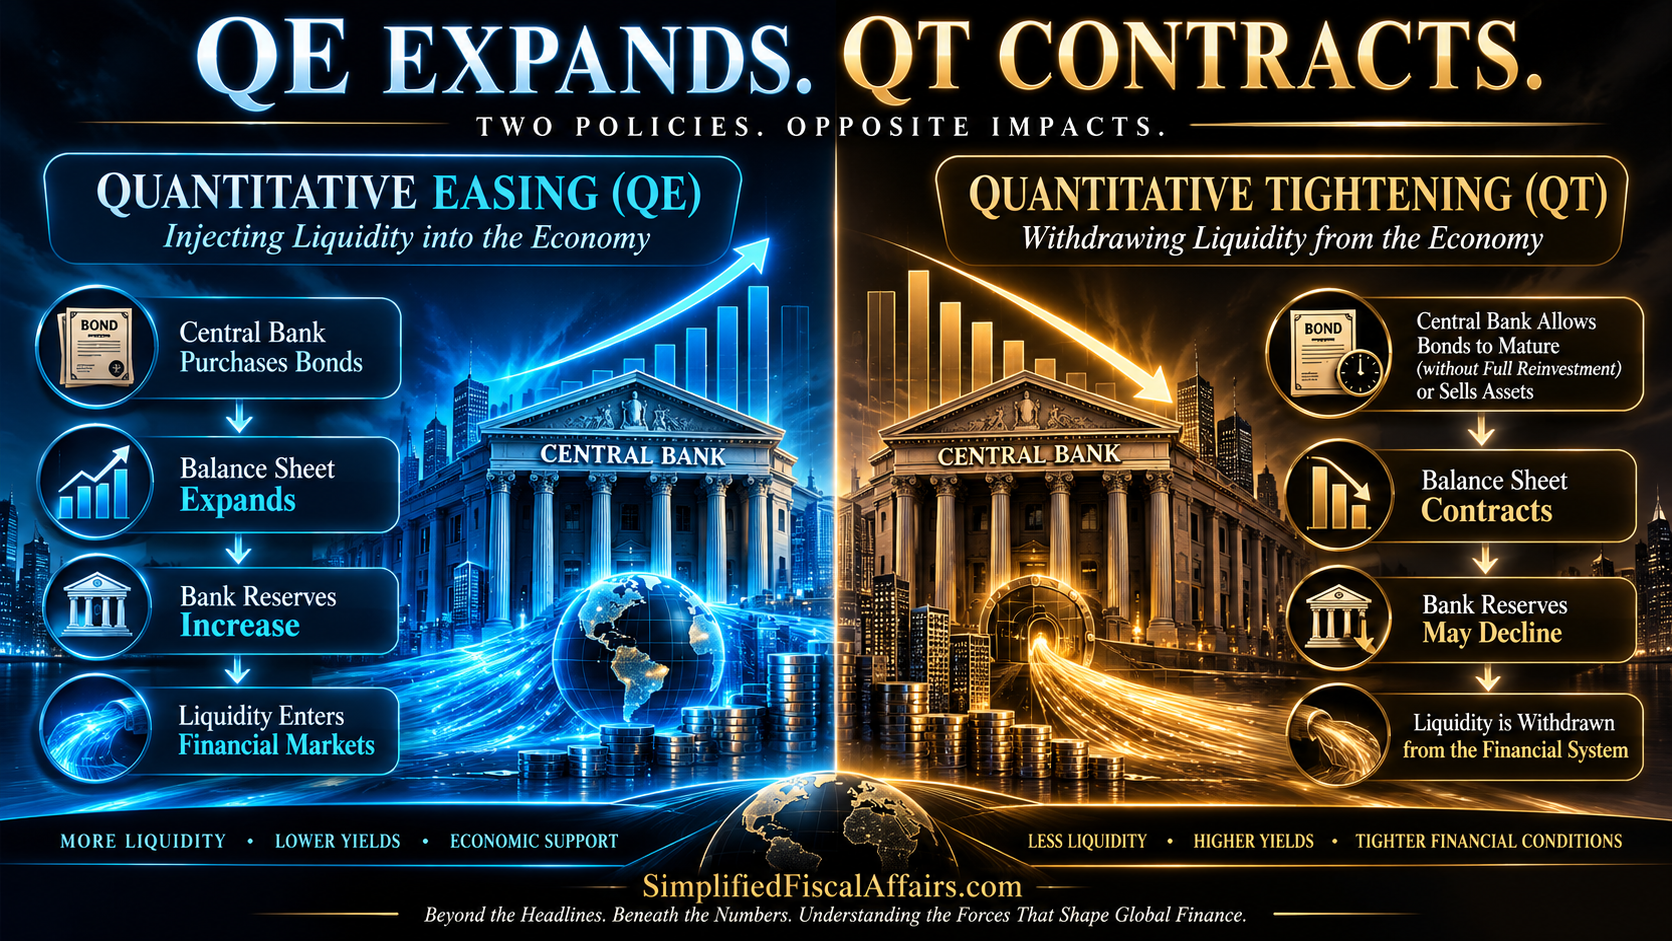
Quantitative Tightening is the process through which a central bank reduces the size of its balance sheet after a period of large-scale asset purchases.
Instead of expanding its holdings of government bonds and other eligible securities, the central bank allows those holdings to decline over time.
This reduction can occur in several ways, including:
- Allowing maturing bonds to roll off without replacing them.
- Selling certain securities into the market, where consistent with the central bank’s policy framework.
The overall objective is to reduce the extraordinary monetary support introduced during earlier periods of economic stress.
Why Does QT Become Necessary?
Imagine an economy that has largely recovered.
Employment improves.
Consumer spending strengthens.
Business investment increases.
At the same time, inflation begins rising above the central bank’s target.
Continuing large-scale bond purchases under these conditions may no longer be appropriate.
Instead, policymakers may seek to:
- Normalize monetary policy.
- Reduce excess liquidity.
- Support price stability.
- Reinforce confidence that inflation will remain under control.
QT becomes part of the broader strategy of returning monetary policy toward more typical settings.
How QT Works
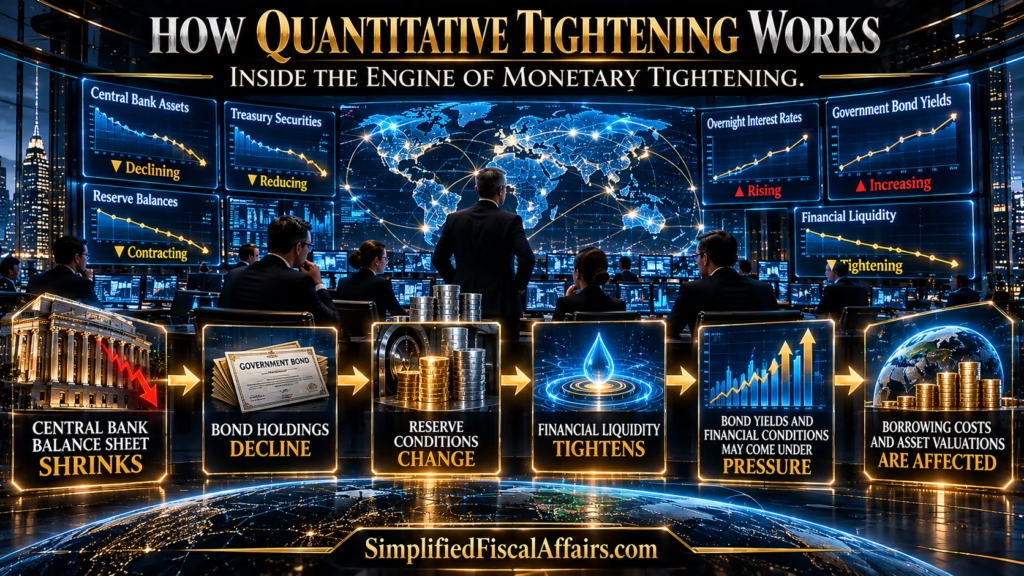
A simplified sequence might look like this.
Step 1
During an earlier period of economic weakness, the central bank accumulated a substantial portfolio of government bonds through QE.
Step 2
Economic conditions improve.
Inflationary pressures strengthen.
Emergency policy support is no longer considered necessary.
Step 3
The central bank announces a balance-sheet reduction plan.
Rather than continuously replacing every maturing bond, it gradually reduces its holdings.
In some circumstances, it may also conduct limited bond sales, depending on its policy approach.
Step 4
The central bank becomes a smaller participant in the bond market than it was during QE.
Step 5
As demand from the central bank declines, market prices and yields may adjust based on broader investor demand and prevailing economic conditions.
Why QT Can Affect Bond Prices
Earlier in this book, we learned an important principle:
Higher demand generally supports higher bond prices.
During QE, the central bank acted as a significant buyer of government bonds.
During QT, that support is reduced.
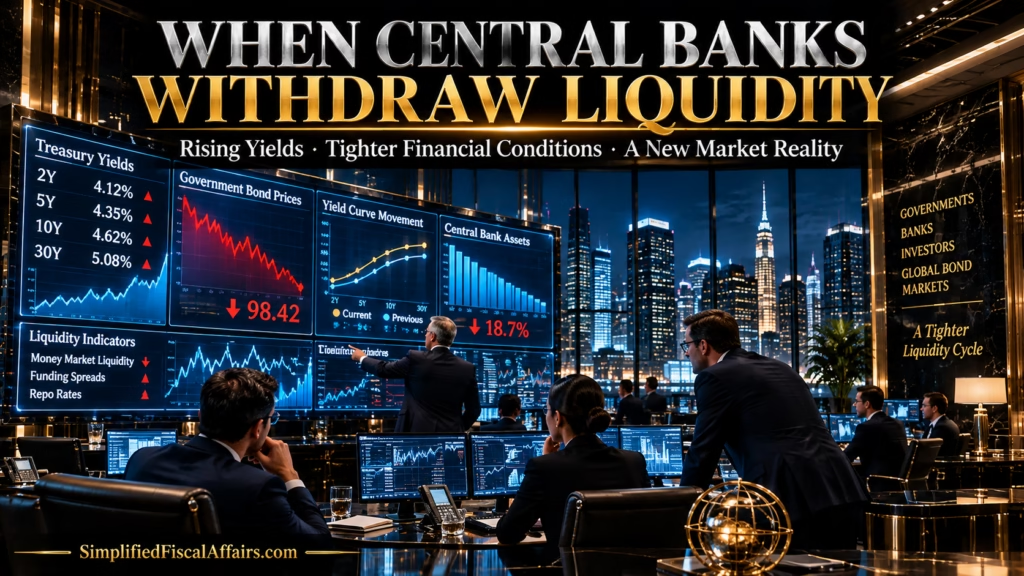
If fewer bonds are purchased by the central bank while market supply remains available, prices may face downward pressure.
Because bond prices and yields generally move in opposite directions:
- Lower bond prices may correspond with higher yields.
- Higher yields can influence borrowing costs throughout the economy.
Actual market outcomes depend on many factors, including inflation, economic growth, investor demand, and expectations.
QT Is Not the Same as Raising Interest Rates
Many new investors assume QT and interest-rate increases are identical.
They are related but distinct policy tools.
Policy Interest Rates
These influence the short-term cost of borrowing across the financial system.
Quantitative Tightening
QT influences broader financial conditions by reducing the central bank’s holdings of financial assets.
A central bank may use one, both, or neither of these tools depending on economic circumstances.
Understanding the distinction helps explain why policymakers often discuss interest-rate decisions separately from balance-sheet policy.
The Role of Expectations
Financial markets often respond not only to what central banks do, but also to what investors expect them to do.
Suppose a central bank announces that QT will begin six months from now.
Even before any balance-sheet reduction occurs, investors may begin adjusting portfolios.
Bond yields, market prices, and broader financial conditions can respond to expectations well in advance of implementation.
This illustrates a recurring theme in financial markets:
Expectations often influence prices before events actually occur.
How QT Influences the Broader Economy
Changes in government bond yields can affect many areas beyond the bond market.
Potential channels include:
- Corporate borrowing costs.
- Mortgage rates.
- Infrastructure financing.
- Bank lending conditions.
- Business investment.
- Household borrowing decisions.
The magnitude of these effects depends on broader economic conditions and investor behaviour.
QT is therefore part of a larger monetary policy framework rather than an isolated action.
Why Communication Matters
Because financial markets respond strongly to expectations, central banks typically communicate QT plans carefully.
Investors pay close attention to announcements regarding:
- The expected pace of balance-sheet reduction.
- Whether maturing bonds will be fully or partially replaced.
- Any planned asset sales.
- Conditions that could alter the programme.
Clear communication helps reduce uncertainty and allows financial markets to adjust more gradually.
Historical Perspective
Following periods of extensive QE in several major economies, central banks eventually faced the challenge of reducing exceptionally large balance sheets.
Rather than removing support abruptly, many policymakers emphasized a gradual and transparent approach.
The experience highlighted an important lesson:
Introducing extraordinary monetary support is only part of the challenge.
Removing that support in an orderly manner requires careful planning and communication.
Institutional Insight
Professional bond managers regularly evaluate questions such as:
- How rapidly is the central bank reducing its balance sheet?
- Is QT already reflected in current bond prices?
- Which maturities may be most affected?
- How are inflation expectations evolving?
- Could changing liquidity conditions influence market volatility?
These considerations help institutions assess both risk and opportunity during periods of monetary policy normalization.
Common Beginner Mistakes
Many investors assume:
“QT always causes bond prices to fall dramatically.”
Not necessarily.
Bond prices are influenced by multiple factors, including inflation, economic growth, investor demand, fiscal policy, and global developments.
QT is one important influence, but it does not determine market outcomes on its own.
Another misconception is:
“QT means the economy is in trouble.”
In many cases, QT reflects policymakers’ assessment that emergency support is no longer required.
Its purpose is often to help return monetary policy toward more normal conditions while pursuing price stability.
Professional Investor’s Checklist
Before evaluating the potential effects of QT, experienced investors often ask:
✔ Is QT occurring alongside interest-rate increases or decreases?
✔ How large is the central bank’s balance sheet?
✔ What pace of reduction has been announced?
✔ How are inflation expectations evolving?
✔ Are current bond yields already incorporating expected policy changes?
✔ What impact could changing liquidity conditions have on portfolio risk?
Chapter Summary
Quantitative Tightening is the process by which central banks reduce the size of their balance sheets after periods of extraordinary asset purchases.
Unlike Quantitative Easing, which expands central bank holdings to support financial conditions, Quantitative Tightening gradually removes that support by allowing assets to mature without full replacement or, in some circumstances, by selling securities.
QT can influence bond prices, yields, liquidity, and borrowing costs, but its effects depend on a wide range of economic and financial factors.
For investors, understanding QT is essential because it represents the transition from crisis-era monetary policy toward a more normalized financial environment.
Successful bond investing requires monitoring not only interest-rate decisions but also the evolution of central bank balance-sheet policies.
← Previous Chapter The Liquidity Engine: Quantitative Easing Explained – XIII
Next Chapter →Duration Explained – XV
Coming Next
Chapter 15 – Duration Explained: Measuring How Sensitive Bonds Are to Changes in Interest Rates
In the next chapter, you’ll discover:
- What duration really measures.
- Why two bonds with the same maturity can respond differently to interest-rate changes.
- The difference between maturity and duration.
- How professional portfolio managers use duration to manage interest-rate risk.
- Why duration is one of the most important concepts in institutional fixed-income investing.
By the end of the next chapter, you’ll understand why experienced bond managers often discuss duration before they discuss returns, and how this single concept helps them estimate the impact of changing interest rates on a bond portfolio.